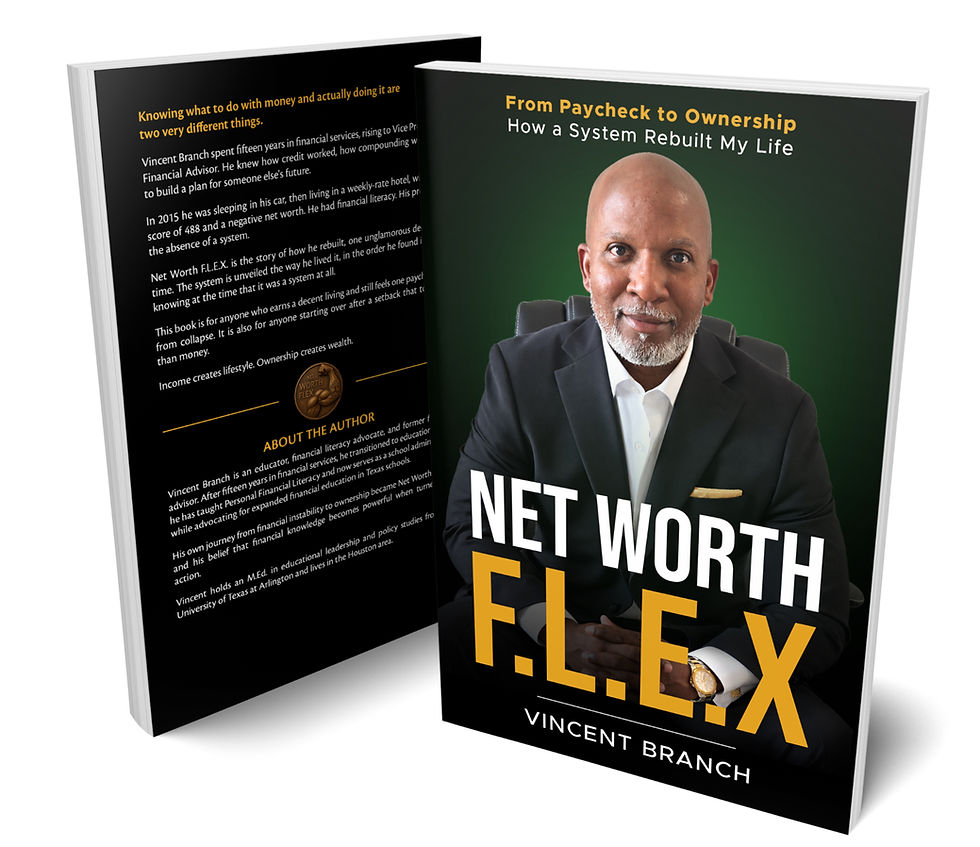
Overview
Net Worth F.L.E.X. is the story of how a financial operating system was born. My transformation from negative net worth and a 488 credit score to financial freedom and ownership serves as a case study that demonstrates how the system works.
In August 2014, I left a fifteen-year career in financial services to become a teacher. Four months later, my marriage ended, and I found myself with a negative net worth, no stable housing, and payday loans draining my paycheck before I ever saw it. Knowing about money had not been enough. I needed a way to turn what I knew into consistent action and measurable progress.
The book follows that collapse through the rebuilding of my life: an 800-plus credit score, multiple income streams, a seven-figure net worth, and a path from paycheck dependence toward ownership. Along the way, the decisions and practices that moved me forward repeated often enough to reveal a structure: Net Worth F.L.E.X.
I named the framework after the fact. I lived the Moves before I had language for them.
This is the story of the system I discovered through that comeback, and how readers can use its four phases and ten Moves to build their own progress.
The story is mine. The system is yours to use.
Problems the Book Solves
This book addresses the real issue:
Many people do not struggle financially because they lack effort, motivation, or knowledge. They struggle because they lack a system that turns what they know into informed decisions, consistent action, and measurable progress toward their financial goals..
Most personal finance books assume:
-
Motivation solves structural problems
-
Income alone leads to wealth
-
One-time fixes outperform systems
-
Knowing = Doing
Here are some data that support my argument that income and knowledge alone do not guarantee better financial outcomes.
1. Even high income does not guarantee financial stability.
In 2024, 20% of households earning more than $150,000 lived paycheck to paycheck, defined as spending more than 95% of household income on necessities. This supports my point that financial struggle cannot always be attributed to low income, laziness, or a lack of ambition.
Source: Bank of America Institute, “Paycheck to Paycheck: What, Who, Where, Why?”
2. More than one-quarter of Americans spend beyond their income.
The 2024 National Financial Capability Study found that 26% of Americans reported spending more than they earned, up from roughly 18%–20% in previous surveys. The nationally representative study included more than 25,500 adults and found that middle-income households were experiencing particular pressure.
Source: FINRA Investor Education Foundation, 2024 National Financial Capability Study
3. Systems substantially improve financial execution.
Among approximately five million workers in Vanguard-administered retirement plans, 94% participated when their plans used automatic enrollment, compared with only 64% in plans requiring employees to enroll themselves. The 30-percentage-point difference demonstrates how changing the system, not necessarily the person’s knowledge or motivation, can dramatically change financial behavior.
Source: Vanguard, How America Saves 2026